

US financial hegemony is anchored not so much on the dollar as a currency as on the attraction of dollar-denominated financial assets.
As Robert Armstrong put it a few days ago:
When we talk about American financial hegemony, we almost always talk about the US dollar. The resilience of the dollar system is the subject of continuous speculation. But there is a better way to frame the issue: the US’s role as the world’s indispensable investment destination. The world’s savings are pulled to the US as if by economic gravity, crowding into American stocks and bonds and providing its economy with a key support. If the gravity should weaken, the consequences would be large.
As Armstrong goes on to point out, US equities (risky assets) and US Treasuries (supposedly safe assets) have hitherto formed a complimentary sandwich.
Huge deficits in the public sector shovel surpluses inot the private sectoral accounts. Equities ride high. In risk-on phases equities dominated. At times of stress, conversely, investors shifted not out of the dollar and dollar-assets but from equities to Treasuries.
This inverse correlation is not a natural feature of the world. It is the result of a series of deeply held expectations. As Wei Li global chief investment strategies for BlackRock has pointed out, in the current moment, the relationship has broken down.
Bond yields have risen sharply, with 30-year Treasury yields reaching a 19-year high above 5.30 per cent this month. Yet equity markets have kept marching higher, with the S&P 500 only just below record highs hit earlier this month. Traditionally, higher government bond yields should weigh on equities by increasing the cost of capital and raising the rates that are used to discount future earnings in valuations. Equally, when equity markets came under pressure, investors expected bond yields to fall as government bonds rallied. Recently, both relationships have become less reliable.
What is going on?
One answer is to point to the relentless boosterism around tech stocks, which is wrenching the market’s sense of reality out of joint. But there is also reason to think that something profound has shifted on the side of Treasuries, the supposedly safe anchor of the dollar system.
Thanks to FTAV’s excellent further reading links I came across a powerful paper by Stanford Finance Professor Hanno Lustig for the Aspen Economic Strategy Group, that provides a compelling narrative of the progressive erosion of the status of US Treasuries as safe assets. In what follows I will quote from the paper with some explanatory commentary.
For decades, the US has been the world’s safe-asset provider, and the dollar has been the world’s reserve currency. As a result, global investors were willing to pay a premium for US Treasurys. US taxpayers benefited because this premium lowered the federal government’s cost of funding. That premium has been eroded in the last few years. Pre-2020, the safe-asset model was a good fit: Treasurys traded at a premium to close substitutes, hedged equity risk, and rallied during stress episodes. Post-2020 each of these predictions has failed.
The most basic feature of a safe asset is presumably that investors are willing to pay more for it than they are for less safe alternatives. In the case of bonds, this implies lower yields. As Lustig point out, and is abdundantly evident from even a casual inspection of bond yields, this no longer holds.
US Treasurys are no longer expensive compared to close substitutes like German sovereign bonds or AAA US corporate bonds, especially at longer maturities.
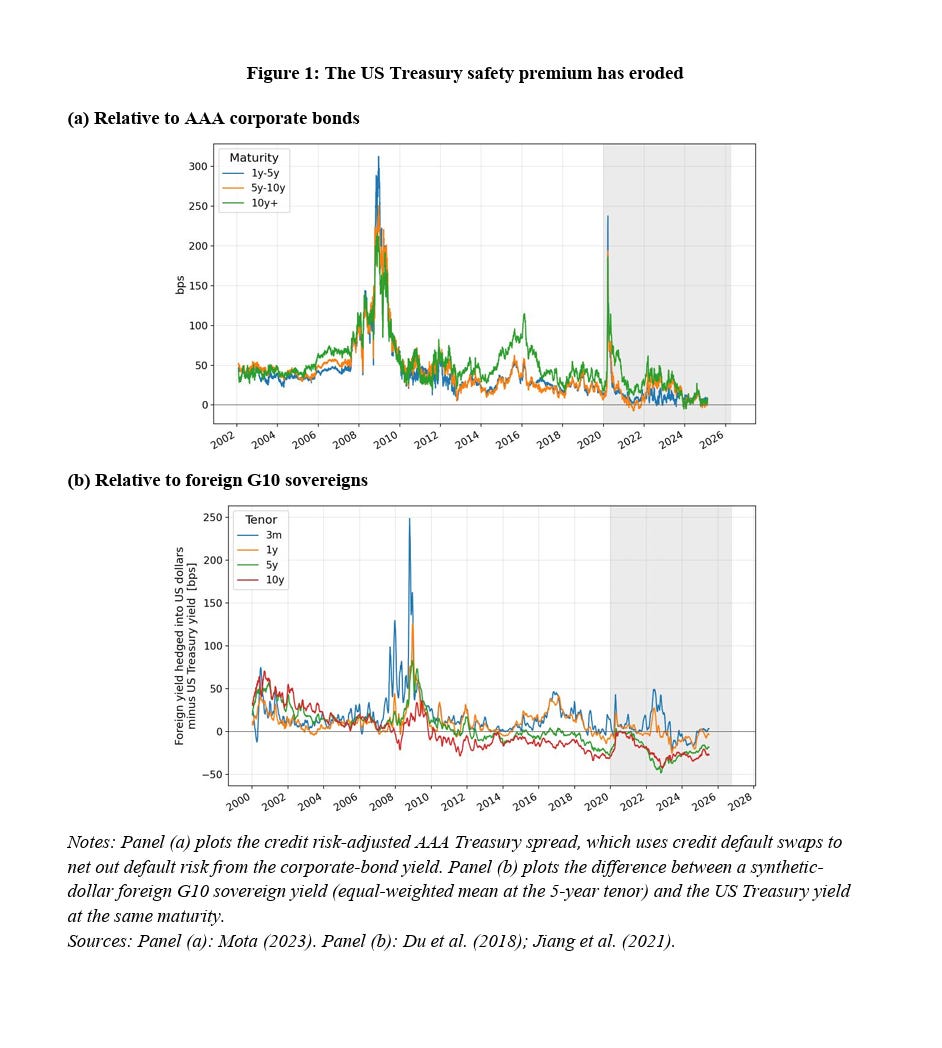
As the bottom panel shows, not only do Treasurys no longer command a premium, they actually trade at a discount to many G10 sovereigns.
Furthermore, as asset prices fluctuate, Treasurys no longer function as a hedge:
the US stock–bond correlation turned positive in 2020. US Treasury allocations no longer hedge the equity risk in an investor’s portfolio.
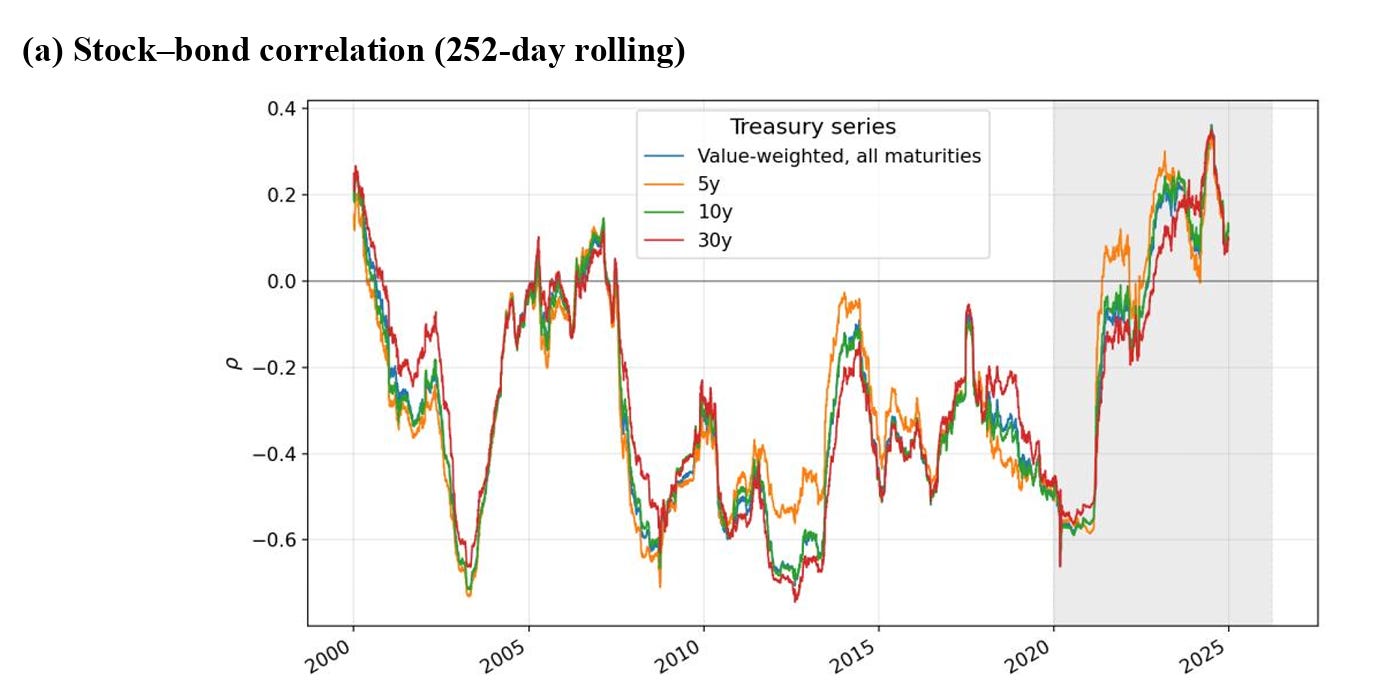
And this then has implications for investor behavior. Whereas the inverse correlation was formerly reinforced by investor behavior - at times of stress they fled INTO not OUT of US bonds. Now, this no longer holds.
there is increasing evidence that investors no longer flee to the safety of Treasurys when volatility spikes in financial markets. An example of this was the arrival of COVID-19 in March 2020, when the 10-year Treasury yield spiked by 68 basis points in just eight trading days between March 9 and March 18.
As Lustig spells out, to make the case for a shift in the safe asset status of Treasuries, it is not enough to show that the correlation has shifted. After all, if the type of shock that is hitting the economy hits both bonds and equities, then the correlation will change. So, to uphold his argument, Lustig then offers two more technical arguments.
In the framework of Campbell, Sunderam, and Viceira (2017) and Campbell, Pflueger, and Viceira (2020), the sign of the stock–bond correlation is determined by the mix of shocks hitting the economy. Supply shocks move stocks and bonds in the same direction; demand shocks move them in opposite directions. The post-2021 period was unusually supply-shock heavy: pandemic supply chains, energy, tariffs. The correlation flip may be a macro fact about the shock mix, not a repricing of sovereign risk, and it will revert once demand shocks reassert themselves. A change in the shock mix would flip the sign of the correlation without any change in what investors believe about the safety of US government debt. Supply shocks are bad news for both stocks and nominal bonds. Two features of the data speak against the pure shock-mix reading. First, the correlation flip loads on the wrong component of the yield. Acharya and Laarits (2025) decompose the Treasury yield into a frictionless risk-free rate, a credit-risk component proxied by the sovereign CDS spread, and the Treasury premium/convenience yield, and then decompose the aggregate stock–bond covariance into the three corresponding terms. The covariance attributable to the Treasury premium component does most of the work. Supply shocks move expected inflation and real rates, and that is where a change in the shock mix should show up in the covariance. It does not. Second, the flip is maturity-specific in a way a macro shock mix cannot easily generate. Acharya and Laarits (2026) apply the same decomposition to the April 2025 tariff episode and find that the rise in stock–bond covariance is concentrated in the Treasury premium component of long bonds, while the short end of the curve retained both its Treasury premium and its hedging property accompanied by a rotation of safe-asset investors toward shorter maturities. The shock mix does not explain why the ten-year should stop hedging while the two-year continues to. Duration-specific fiscal risk does exactly that, and the same term-structure signature appears twice more in this paper: the Treasury-premium reversal in Panel (b) of figure 1 is concentrated at the 5- and 10-year tenors, and the Treasury’s migration toward bill issuance documented in section 4 is the quantity counterpart of the same repricing.
The basic message is dramatic: the operating logic of the Treasury market, the largest and most foundational market of the global system, is no longer that of a market for safe asssets. Global investors now regard the $32 trillion in US debt in public hands, as risky.
And part of the problem, part of what makes them risky, is that the US authorities stubbornly refuse to take seriously this new reality. Bessent’s cack-handed interventions of the last weeks only reinforce this point.
Bond investors and monetary policymakers now disagree on how to price US government debt. Bond investors increasingly question the safety of US Treasurys, and they have re-priced Treasurys as a risky claim. Central bankers and financial regulators have not adjusted: their models and financial regulation still treat government debt as unambiguously safe.
The Fed and now the Treasury too have on many occasions refused to accept the verdict of the market and have insisted that sharp movements in yields are ultimately explained not by fundamental but by technical issues of market plumbing, liquidity etc. Most recently, Bessent’s interventions are explicitly premised on the idea that the market is mis-pricing US Treasurys, particularly at the long end.
So far, Lustig is rehearsing well known observations about financial markets. The plot thickens as he begins to spell out the “real-world consequences”, of the disagreement over bond prices.
When investors sell off Treasury bonds in response to fiscal news, monetary policymakers operating under a safe-debt view read the move as a “bond-market plumbing” problem and respond by deploying some of their balance-sheet capacity to purchase US Treasurys.
Even the US Treasury is now intervening to correct “plumbing issues”.
Market participants, by contrast, drove the sell-off themselves: they sold Treasurys because they read the fiscal news as implying US Treasurys are risky, and the resulting price decline is price discovery, not dysfunction.
The result is an intensifying spiral or perverse interactions. Bondholders no longer trust that there is any chance of a fiscal policy or monetary policy response to large deficits. So “bad fiscal” news hits bond prices. Rising yields then intensify the fiscal pressure. And, to add to the perversity, increasing fiscal pressures actually DOES begin to generate plumbing issues in the financial system, providing confirmation for the diagnosis by the Fed and Treasury, even as that diagnosis ignores the fundamental issues at stake. As Lusting puts it:
Fiscal and bond-market plumbing problems are intertwined. The erosion of the Treasury premium at the long end of the yield curve has pushed the Treasury toward shorter maturities, raising rollover risk. Primary dealers, the large banks that buy directly from the Treasury at auction and resell to investors, are balance-sheet constrained after the 2008 Global Financial Crisis (GFC); hedge funds have partly replaced primary dealers and absorbed a significant fraction of the Treasury issuance. Together these factors raise the probability that a failed auction or rollover spike forces emergency measures precisely when market confidence is most fragile.
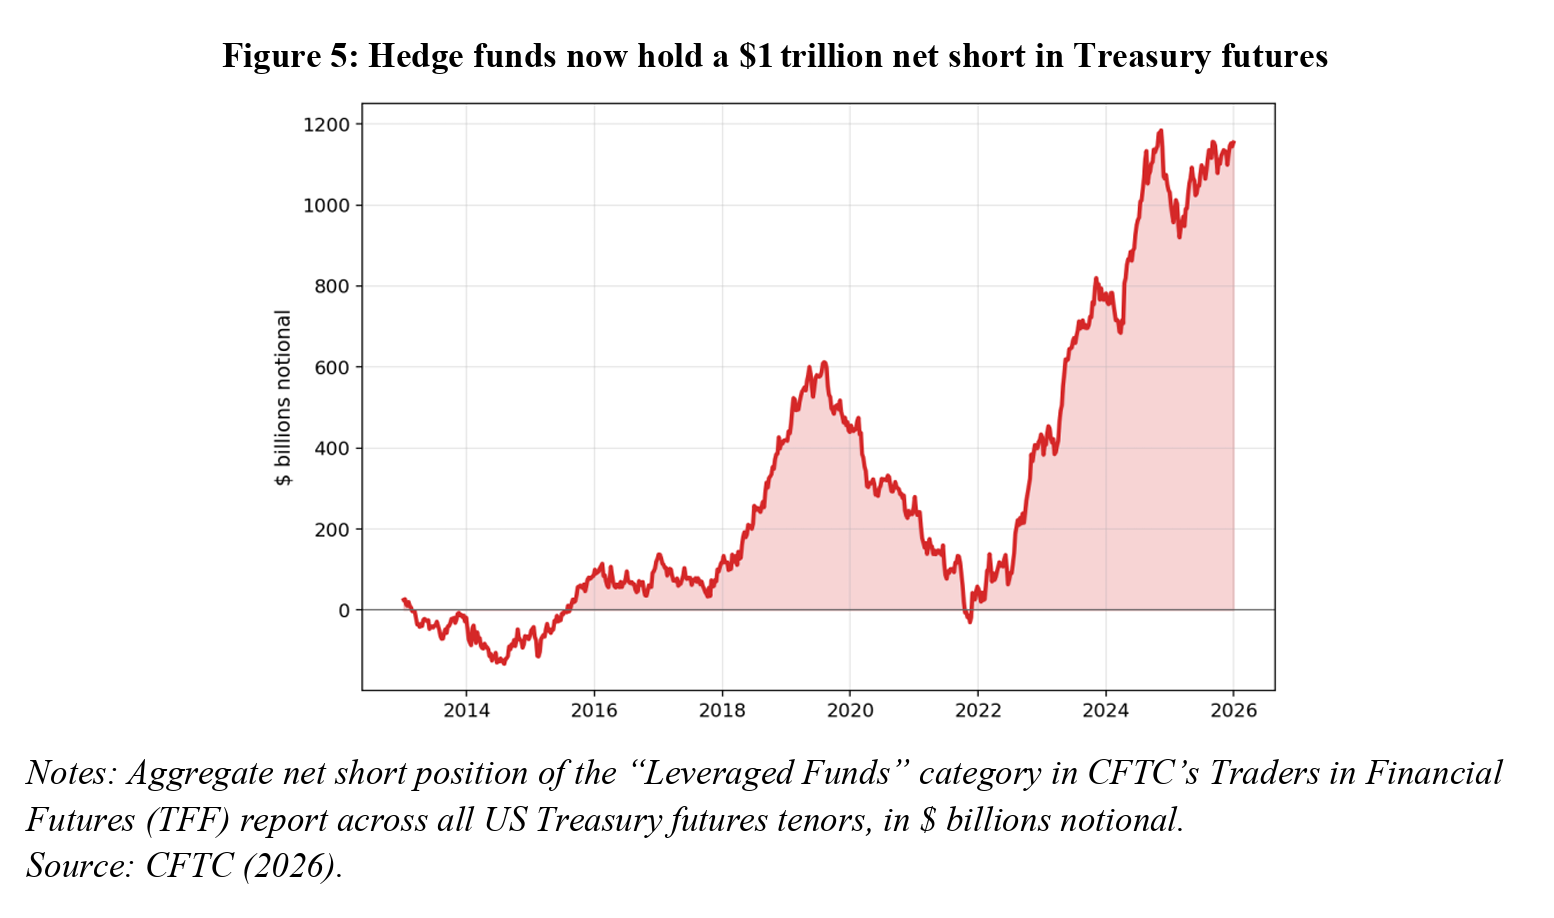
Lustig’s account thus connects to the Treasury market fragility which I discussed in an earlier post.
The result, Lusting insists, will be a spiral of increasing financial repression.
Lustig’s remarks are addressed to the Fed:
If the Fed persists in interpreting Treasury sell-offs through the safe-debt frame, it risks both suppressing the price signal and absorbing a growing share of issuance onto its balance sheet, mirroring the Bank of Japan (Chien et al. 2025a) and the Eurosystem (Chien et al. 2025b). In both cases, these central banks help sovereigns borrow at below-market rates, a form of financial repression (Gómez-Cram et al. 2026). … The historical record is sobering. From 1942 through 1951, the Federal Reserve capped longbond yields at 2.5 percent to help finance the war effort. When inflation reached 14 percent in 1947, American savers, retirees, life-insurance policyholders, and pension funds incurred significant real losses until the 1951 Treasury–Federal Reserve Accord ended the peg. … the more the Fed absorbs fiscal news as “plumbing,” the further along this path the US moves. There is no clear exit strategy from financial repression. The longer the Fed waits to restore price discovery, the more difficult it will be to do so without a disruptive market adjustment.
They are even more acute if we consider the US Treasury’s interventions.
The question for this week is how will Warsh in his address to the Jackson Hole meeting? Reuters links Lustig directly to Warsh’s dilemma:
Warsh has long criticized the Fed’s large-scale asset purchases, arguing such interventions should be reserved for genuine market dysfunction, with rate policy driving the employment and inflation mandates. Stanford finance professor Hanno Lustig contends in a recent Aspen Institute paper that the question of how safe Treasuries are has become a key dividing line. Trends in government-bond pricing and other factors show that markets already treat Treasuries as risky, he says, while the Fed and policymakers still act as if they’re safe. This distinction matters because when yields spike on fiscal worries, the Fed intervenes to calm markets on the grounds that market dysfunction is causing the problem rather than worries about investment safety, he says — a decision that stands to muffle the price signals that would otherwise warn of unsustainable debt. Ultimately, many analysts and portfolio managers agree that tweaks to buybacks, issuance and market plumbing can’t fix a longstanding problem that has recently gotten much more acute — persistent fiscal deficits. The best case is for policymakers to embrace debt reduction driven by stronger growth, Garvey said — a choice that implies some hard choices in Washington. “It’ll be very difficult to reduce the deficit without taking some fiscal action,” he said, “which requires either higher taxes or lower spending.”
Financial repression or austerity - is this the question? Does either really seem likely under MAGA. As I argued yesterday, are we not painting in dark, dramatic colors, a state of affairs that is much better characterized as a grey zone, somewhere between obfuscation on the one side and histrionics on the other?
I love putting out Chartbook. I am particularly pleased that it goes out for free to thousands of subscribers around the world. But, writing this newsletter takes a lot of work. If you are enjoying it and would like to support the project, sign up for one of the subscription options here. It is the equivalent of a fancy cup of coffee per month!
I think this piece pushes the evidence a bit too far. There is an important distinction between declining willingness to hold long-duration US government debt and erosion of the international power of the dollar.
If investors demand a higher yield to hold 10- or 30-year Treasuries, that may mean the US is losing some of the extraordinary borrowing privilege it has historically enjoyed. Given persistent deficits, inflation risk and enormous duration supply, that would hardly be surprising. But it does not follow that the dollar itself is losing its central role.
The latest BIS survey makes the distinction particularly stark. The dollar was on one side of 89.2% of all FX transactions in 2025, and every one of the ten most-traded currency pairs involved USD. That is dollar power in a fairly literal sense. Even when neither party ultimately wants to hold dollars, routing the transaction through the dollar is generally the most efficient path because of the depth and liquidity of dollar markets.
A Treasury is an asset denominated in dollars; it is not the dollar. Selling a Treasury initially leaves the investor with dollars, after which there is a separate decision about where to invest them. And the currency in which we choose to save is itself distinct from the currency through which the world transacts.
There may be a good argument that the US is losing some of its privilege to issue long-term debt unusually cheaply. That is economically important. But it seems a considerable leap from there to evidence of declining dollar power. The evidence presented here strikes me as much stronger for the former than the latter.
This is the main terrain within markets at the moment, so Professor Tooze is spot on to feature two days running. As a practitioner, not an academic, of 35 years standing, my point to analysts, portfolio managers and allocators has always been that there is not necessarily a natural correlation between bond yields and equity returns, nor necessarily a tag-in, tag-out reliable behaviour. The fracture in that dubious framework explains the sub-cutaneous unease in tradable markets.